Blog
Why Use a Mortgage Broker GTA – Smart Financial Decisions


Nearly half of Canadian homebuyers turn to mortgage brokers for guidance through the maze of financing options. With property prices and lending rules in Canada changing every year, finding the right path can feel daunting. Understanding exactly how an Ontario mortgage broker can simplify the process gives buyers an edge in securing solutions that fit their unique needs and unlock meaningful savings.
Table of Contents
- What An Ontario Mortgage Broker Does
- Types Of Mortgage Solutions Available
- How Brokers Secure The Best Deals
- Comparing Brokers Versus Direct Lenders
- Important Costs And Regulatory Protections
- Avoiding Common Mortgage Application Mistakes
Key Takeaways
| Point | Details |
|---|---|
| Role of Mortgage Brokers | Mortgage brokers in Ontario connect homebuyers with suitable lending options, providing tailored financial solutions and expert guidance throughout the mortgage process. |
| Types of Mortgage Solutions | Various mortgage types, including fixed-rate, variable-rate, and adjustable-rate options, cater to diverse financial needs, allowing for informed decision-making. |
| Negotiation Expertise | Brokers use market analysis and lender relationships to negotiate competitive rates, maximizing savings for borrowers over the loan’s duration. |
| Regulatory Protections | Ontario’s regulatory framework ensures that mortgage brokers adhere to strict standards, safeguarding consumer interests and promoting transparent lending practices. |
What an Ontario Mortgage Broker Does
A mortgage broker in Ontario serves as a critical financial intermediary who connects potential homebuyers with appropriate lending solutions. These licensed professionals play a crucial role in navigating the complex mortgage landscape, helping clients secure financing tailored to their unique financial circumstances.
Mortgage brokers in Ontario are regulated professionals who work independently from specific banks, which allows them to explore mortgage options across multiple lenders. Their primary responsibilities include:
- Assessing a client’s financial profile and borrowing capacity
- Comparing mortgage rates and terms from various financial institutions
- Providing personalized mortgage recommendations
- Guiding clients through the application and approval process
- Negotiating competitive interest rates on behalf of borrowers
Through their extensive network and deep understanding of the lending market, mortgage brokers offer significant advantages that traditional bank representatives cannot. They have access to a broader range of mortgage products, including options from private lenders and alternative financing sources that might not be readily available through standard banking channels. This flexibility enables them to find creative solutions for clients with unique financial situations, such as self-employed individuals, those with non-traditional income streams, or borrowers with complex credit histories.
Under the Mortgage Brokerages, Lenders and Administrators Act, 2006, Ontario mortgage brokers must meet stringent professional standards. They are required to complete specific educational requirements, maintain professional licensing, and adhere to strict ethical guidelines that protect consumer interests. This regulatory framework ensures that mortgage brokers provide transparent, reliable, and client-focused financial advice throughout the mortgage acquisition process.
Types of Mortgage Solutions Available
In the complex world of home financing, borrowers have access to multiple mortgage solutions designed to accommodate diverse financial needs and circumstances. Canadian mortgage options range from traditional to innovative lending approaches, providing flexibility for homeowners and potential buyers across Ontario.
The primary mortgage types include:
- Fixed-Rate Mortgages: Offer stability with consistent interest rates throughout the loan term
- Variable-Rate Mortgages: Interest rates fluctuate based on market conditions
- Adjustable-Rate Mortgages: Combine elements of fixed and variable rate structures
- Open Mortgages: Allow additional payments or complete loan repayment without penalties
- Closed Mortgages: Provide lower interest rates with restrictions on prepayment
For individuals with unique financial profiles, alternative mortgage solutions offer tailored approaches beyond traditional lending models. These specialized options include private mortgages, home equity lines of credit, and solutions designed for self-employed professionals, investors, and those with non-traditional income streams.
Understanding the nuances of each mortgage type is crucial for making informed financial decisions. Factors like personal income, credit history, employment status, and long-term financial goals will significantly influence which mortgage solution best suits an individual’s needs. Working with a knowledgeable mortgage broker can help navigate these complex options, ensuring borrowers select the most advantageous mortgage strategy for their specific circumstances.
How Brokers Secure the Best Deals
Mortgage brokers are strategic financial professionals who excel at negotiating competitive lending terms across multiple financial institutions. Their expertise goes far beyond simply connecting borrowers with lenders, involving sophisticated strategies that can save clients significant money over the lifetime of their mortgage.
The key methods brokers use to secure optimal deals include:
- Comprehensive market analysis of current lending rates
- Detailed assessment of a client’s unique financial profile
- Strategic matching with lenders most likely to offer favourable terms
- Leveraging professional relationships with multiple financial institutions
- Negotiating rate discounts and flexible mortgage conditions
These professionals understand that each borrower’s financial situation is unique. Alternative mortgage solutions provide flexible pathways for clients who might not qualify through traditional banking channels, such as self-employed individuals, those with non-traditional income, or clients with complex credit histories.
Brokers invest significant time researching lender preferences, understanding nuanced qualification criteria, and identifying opportune moments to negotiate. Their deep industry knowledge allows them to anticipate potential challenges, proactively address potential roadblocks, and structure mortgage applications that maximize a client’s chances of approval while securing the most competitive interest rates available in the current market.
Comparing Brokers Versus Direct Lenders
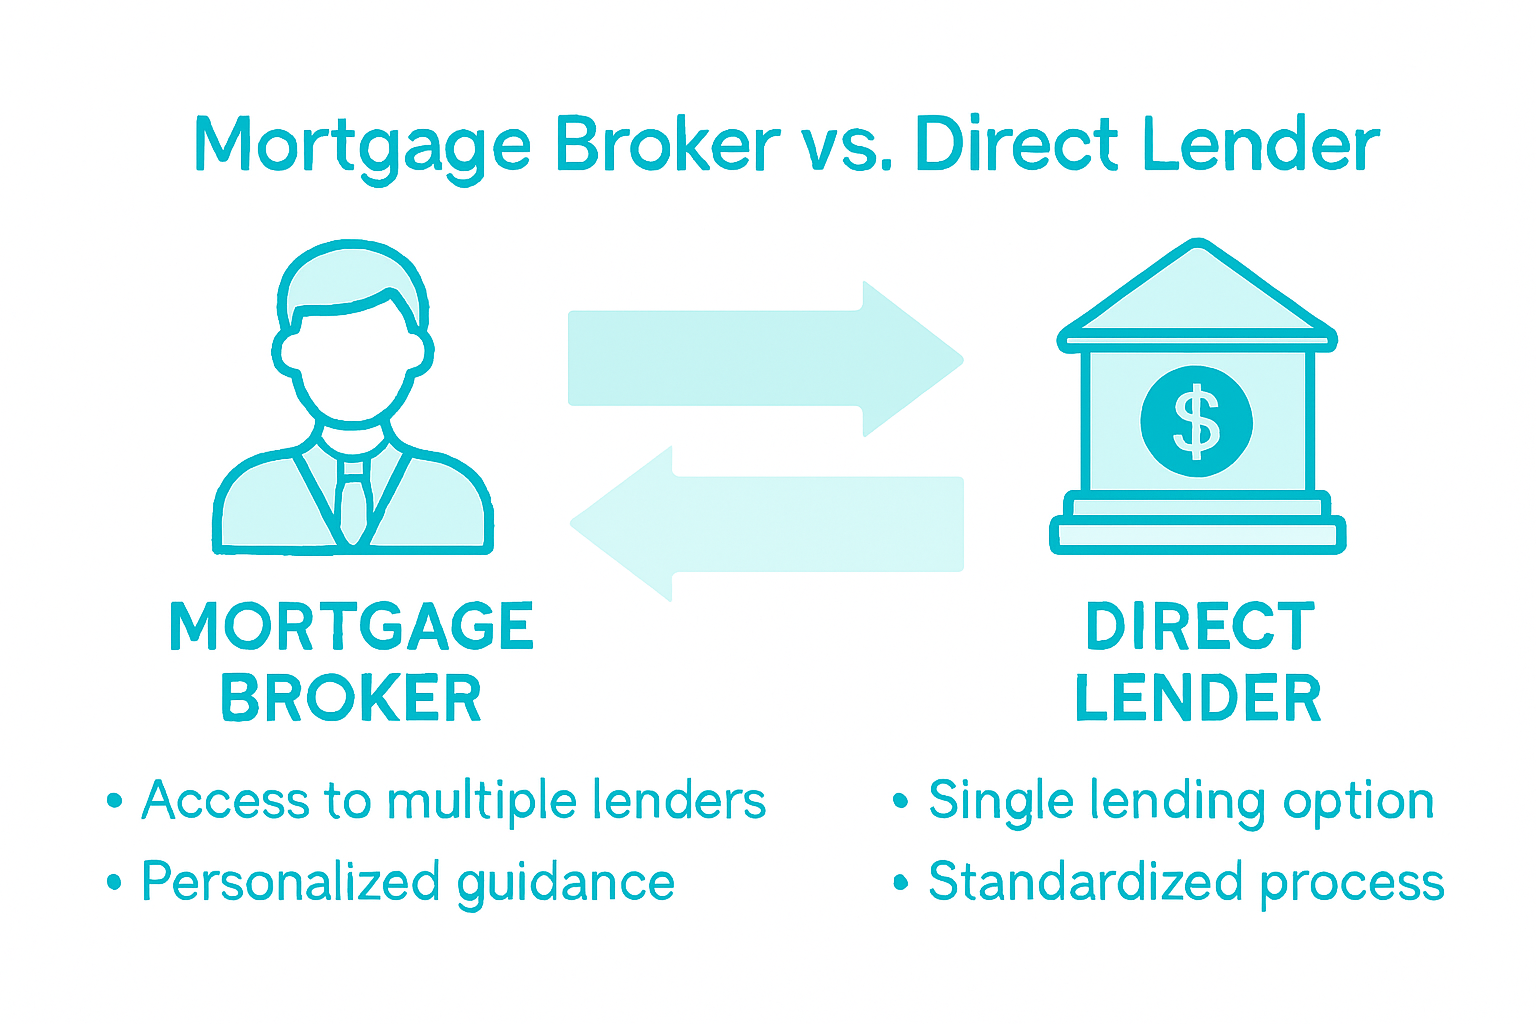
Choosing between a mortgage broker and a direct lender involves understanding the fundamental differences in their approach to home financing. While direct lenders represent a single financial institution with limited product offerings, mortgage brokers provide a comprehensive, multi-institutional perspective that can significantly expand a borrower’s options.
Key distinctions between brokers and direct lenders include:
-
Product Range:
- Direct Lenders: Restricted to their own mortgage products
- Brokers: Access to multiple lenders and diverse mortgage solutions
-
Flexibility:
- Direct Lenders: Standardized approval processes
- Brokers: Customized strategies for unique financial situations
-
Rate Negotiation:
- Direct Lenders: Fixed institutional rates
- Brokers: Ability to compare and negotiate competitive rates
Private mortgage lending options provide additional flexibility for borrowers who might not meet traditional lending criteria. These alternative solutions become particularly valuable for self-employed professionals, individuals with complex income structures, or those rebuilding credit.
Ultimately, mortgage brokers offer a more personalized, strategic approach to home financing. They invest time in understanding a client’s unique financial landscape, leveraging professional relationships and market insights to secure terms that direct lenders simply cannot match. By representing the borrower’s interests rather than a single institution’s, brokers create opportunities for more favourable mortgage conditions and potentially significant long-term financial savings.
Important Costs and Regulatory Protections
Navigating the financial landscape of mortgage brokering requires a comprehensive understanding of the regulatory framework designed to protect consumers. In Ontario, mortgage brokers are subject to stringent licensing and oversight requirements that ensure professional standards and client protection.
Key regulatory protections and associated costs include:
-
Licensing Fees:
- Initial broker licensing application
- Annual renewal costs
- Continuing education requirements
-
Consumer Safeguards:
- Mandatory professional conduct standards
- Disclosure requirements for mortgage terms
- Suitability assessments for client recommendations
-
Potential Broker Compensation:
- Lender-paid commissions
- Client-direct service fees
- Transparent fee structures
Private mortgage lending introduces additional regulatory considerations that borrowers must carefully evaluate. The Financial Services Regulatory Authority of Ontario (FSRA) provides oversight to ensure brokers maintain high professional standards, protecting consumers from potential misconduct while ensuring transparent and fair mortgage transactions.
While regulatory costs might seem complex, they ultimately serve to create a secure and reliable mortgage brokering environment. These professional standards protect consumers by mandating thorough background checks, ongoing education, and strict ethical guidelines for mortgage professionals. By understanding these protections, borrowers can confidently navigate the mortgage landscape, knowing that robust regulatory mechanisms are in place to safeguard their financial interests.
Avoiding Common Mortgage Application Mistakes
Understanding the nuanced requirements of mortgage applications can significantly improve a borrower’s chances of approval and secure more favourable lending terms. Most applicants unknowingly make critical errors that can derail their mortgage prospects before they even begin.
Common mortgage application mistakes to avoid include:
-
Financial Documentation Errors:
- Incomplete or outdated income verification
- Missing tax returns or financial statements
- Inconsistent employment documentation
-
Credit Profile Missteps:
- Failing to review credit reports beforehand
- Making large purchases during application process
- Neglecting to address existing credit issues
-
Application Strategy Mistakes:
- Applying with multiple lenders simultaneously
- Misrepresenting income or financial status
- Overlooking mortgage pre-approval processes
Mortgage pre-approval strategies help prospective borrowers understand their lending potential before formally applying. Professional mortgage brokers can provide crucial guidance in navigating these complex requirements, ensuring that applicants present the most compelling financial profile possible.
Prospective borrowers should recognize that mortgage brokerages operate on commission-based compensation models, which means their primary motivation is successfully securing a mortgage that meets the client’s needs. By working closely with experienced professionals and meticulously preparing documentation, applicants can significantly reduce the risk of application rejection and increase their chances of obtaining optimal mortgage terms.
Make Smart Financial Decisions with a Trusted Ontario Mortgage Broker
Navigating the complexities of mortgage options, from private mortgage lenders to alternative income solutions, can be challenging without expert guidance. If you are facing unique financial situations like self-employment, debt consolidation, or investment property financing, understanding your best mortgage solution is crucial. This article highlights how an Ontario mortgage broker can provide personalized strategies to secure competitive rates and avoid costly mistakes.
Miracle Financial is your go-to Vaughan mortgage broker offering expert advice and tailored solutions including refinance strategies and home equity loans in Ontario. We combine industry knowledge with innovative technology to help you achieve fast approvals and better financial outcomes.
Don’t let complex mortgage options hold you back. Discover how working with the Best mortgage broker GTA can save you time, money, and stress. Visit Miracle Financial today and take the first step towards smart mortgage planning and financial freedom.
Frequently Asked Questions
What are the benefits of using a mortgage broker?
Using a mortgage broker allows you to access a wider range of mortgage products from multiple lenders, get personalized advice based on your financial situation, and benefit from their negotiation skills to secure better rates and terms.
How do mortgage brokers compare to direct lenders?
Mortgage brokers work with various lenders to provide a broader selection of mortgage options, whereas direct lenders offer products from a single financial institution. Brokers can negotiate terms and find tailored solutions that suit diverse financial needs.
What types of mortgage solutions can a broker provide?
Mortgage brokers can offer a wide array of mortgage solutions, including fixed-rate, variable-rate, adjustable-rate, open, and closed mortgages, as well as alternative options for clients with unique circumstances, such as private mortgages or home equity lines of credit.
How can I avoid common mistakes when applying for a mortgage through a broker?
To avoid mistakes, ensure that you have complete and accurate financial documentation ready, review your credit profile, and consider obtaining mortgage pre-approval. Additionally, work closely with your broker to present a compelling application that highlights your strengths as a borrower.